Gold Coast Airbnb Body Corporate Rules: 2026 Owner’s Guide
- 14 September 2026
- Blog
Can your body corporate actually ban you from listing your Gold Coast apartment on Airbnb in 2026? It's a question that keeps... Read More
 by BNB Booking
What if the safety net protecting your Brisbane investment is more of a delicate spiderweb than a robust shield? You’ve likely invested significant capital and heart into your property, yet the reality of airbnb risk management australia is that many hosts are operating with a false sense of security. Standard home insurance policies often trigger business activity exclusions the moment you take a booking; this leaves you vulnerable to guest damage and complex strata liability claims that could jeopardise your financial future.
We understand the anxiety that comes with letting strangers into your most valuable asset, and we promise to provide you with the strategic clarity needed to navigate these legal and financial hurdles with confidence. This 2026 guide breaks down the latest AirCover evidence standards, explores the impact of Brisbane’s Transitory Accommodation rates, and delivers a must-have checklist for specialist short-term rental insurance. You’ll gain a professional perspective on how to keep your property safe, compliant, and positioned for long-term success in the competitive South East Queensland market.
Many property owners believe that a standard residential home and contents policy provides a safety net for their short-term rental activities. This is a dangerous misconception. In the context of the sharing economy, most major Australian insurers view hosting as a commercial enterprise. The moment you accept payment for a stay, your property transitions from a private residence to a business premises, often triggering a ‘business activity’ exclusion clause hidden deep within your Product Disclosure Statement (PDS).
This exclusion can effectively void your entire policy. If a guest accidentally starts a kitchen fire or a pipe bursts during their stay, your insurer may refuse the claim entirely because they did not agree to cover the increased risks associated with transient guests. For owners in Brisbane and South East Queensland, where tropical storm seasons and high-density strata living add layers of complexity, this lack of coverage is a significant financial gamble. Effective airbnb risk management australia requires moving beyond these basic policies to find coverage that explicitly acknowledges short-term guests.
It is also critical to understand that a platform’s ‘Host Guarantee’ is not a substitute for insurance. Under Australian law, a guarantee is a discretionary promise, not a binding contract of insurance regulated by APRA. This means the platform has the final say on whether to pay out, whereas a dedicated insurance policy provides you with enforceable legal rights and access to the Australian Financial Complaints Authority (AFCA). Relying solely on a platform leaves your most valuable asset exposed to the whims of a corporate policy rather than the protection of Australian law.
The ‘duty of disclosure’ is a fundamental principle of Australian insurance law. You’re legally required to inform your insurer about any change in how your property is used. Failing to notify them that you’re hosting on Airbnb can lead to a total loss of coverage. Consider a scenario in a Brisbane high-rise where a guest leaves a tap running, causing extensive water damage to multiple floors. Without specific short-stay cover, you could be personally liable for hundreds of thousands of dollars in repairs and third-party damages, as standard policies typically exclude ‘malicious act or damage by a tenant or guest’ when the property is used for profit.
It’s vital to distinguish between traditional landlord insurance and short-stay specific policies. Most conventional landlord products are designed for fixed-term tenancies of six to twelve months. They often contain clauses that exclude any claim arising from a stay shorter than 90 days. This makes them fundamentally unfit for the Airbnb model. Ensuring short term rental compliance QLD means securing a policy that uses the correct legal definitions. A ‘tenant’ under a residential lease has different legal obligations and risk profiles than a ‘guest’ under a short-term license to occupy. If your policy doesn’t explicitly use ‘guest’ wording, your claim success is at the mercy of the insurer’s interpretation during the airbnb risk management australia process.
While Airbnb’s AirCover is often marketed as a comprehensive safety net, it’s merely a starting point for sophisticated airbnb risk management australia. As of August 2026, AirCover for Hosts provides up to approximately A$4.4 million in damage protection and A$1.47 million in liability insurance. These figures sound substantial, yet they come with a significant caveat: they are discretionary. Unlike a policy issued by a local provider holding an Australian Financial Services Licence (AFSL), AirCover isn’t a contract of insurance. Airbnb retains the final authority on whether a claim is paid, meaning you lack the enforceable legal rights and access to the Australian Financial Complaints Authority (AFCA) that a regulated policy provides.
Significant gaps remain for the unwary host. AirCover frequently excludes theft by guests if there isn’t clear evidence of a break-in, and it typically lacks ‘loss of income’ protection to cover your mortgage while a property is being repaired. This is particularly concerning given that various state regulations and the mandatory code of conduct often imply a higher standard of third-party protection than a platform guarantee can offer. Securing a local, regulated policy ensures your investment is protected by Australian law, not just a platform’s internal terms of service.
The burden of proof under AirCover is notoriously high. Following updates on April 20, 2026, Airbnb introduced even stricter evidence standards for claims. Hosts must now submit comprehensive documentation within a hard 14-day window after checkout. For Brisbane owners in high-density strata buildings, AirCover’s liability limit of roughly A$1.47 million is often legally insufficient. Many Body Corporate bylaws in South East Queensland specifically require A$20 million in public liability insurance to cover incidents in common areas, a gap that only a specialist Australian policy can fill. Professional Airbnb management in Brisbane can assist in maintaining the rigorous inventory logs required to satisfy these platform evidence rules.
A specialist short-term rental policy offers targeted protections that platforms simply don’t provide. These policies distinguish between accidental damage and malicious damage, ensuring you’re covered if a guest intentionally trashes your interior. Crucially, they include ‘Loss of Rent’ provisions, which maintain your cash flow if a major event renders the home unrentable. Furthermore, these policies often cover legal expenses for Australian tribunal proceedings or court cases, providing a level of professional asset protection that is essential for any serious property investor in 2026.
Effective airbnb risk management australia isn’t a single policy but a multi-layered strategy. It requires a professional understanding of how physical assets, legal liabilities, and cash flow intersect. While platform tools offer basic support, a truly resilient investment relies on three specific pillars of protection that address the unique challenges of the Australian holiday rental market.
Public liability is your primary defence against the most catastrophic financial risks: guest injury lawsuits and third-party claims. In the Australian market, a limit of A$10 million is the absolute minimum, though A$20 million has become the industry standard for sophisticated hosts. This is especially true for Brisbane strata buildings where Body Corporate rules often mandate high levels of cover for incidents in common areas like pools, gyms, or lifts. According to the Insurance Council of Australia, securing specialist landlord insurance is essential to cover these scenarios, as standard home policies often lack the necessary scope for commercial guest stays. Regular inspections are vital to mitigate ‘trip and fall’ claims, ensuring that loose rugs or faulty balcony railings don’t become million-dollar liabilities.
Protecting your optimised listing styling involves more than just a standard contents policy. High-end furniture, bespoke decor, and expensive electronics require specific coverage for accidental damage and, crucially, ‘mysterious disappearance’. This latter point is a common AirCover exclusion; if a guest leaves and a designer lamp or high-end soundbar is missing without signs of a break-in, platform guarantees often fail to pay out. You need a policy that covers high-turnover accidents like red wine spills on wool carpets or damage to kitchen appliances. Professional airbnb risk management australia means having a detailed inventory that reflects the true replacement value of every item in your SEQ investment, ensuring you aren’t out of pocket when accidents occur.
The final pillar is revenue protection. This ensures your income stream remains stable even if a guest cancels at the last minute or a ‘stop-work’ event occurs. If a guest causes significant damage that makes the property unrentable for several weeks, revenue protection covers that lost income based on your booking history. It bridges the gap between a physical repair and your ongoing mortgage obligations, providing the financial breathing room needed to maintain a high-performing rental without dipping into your personal savings.
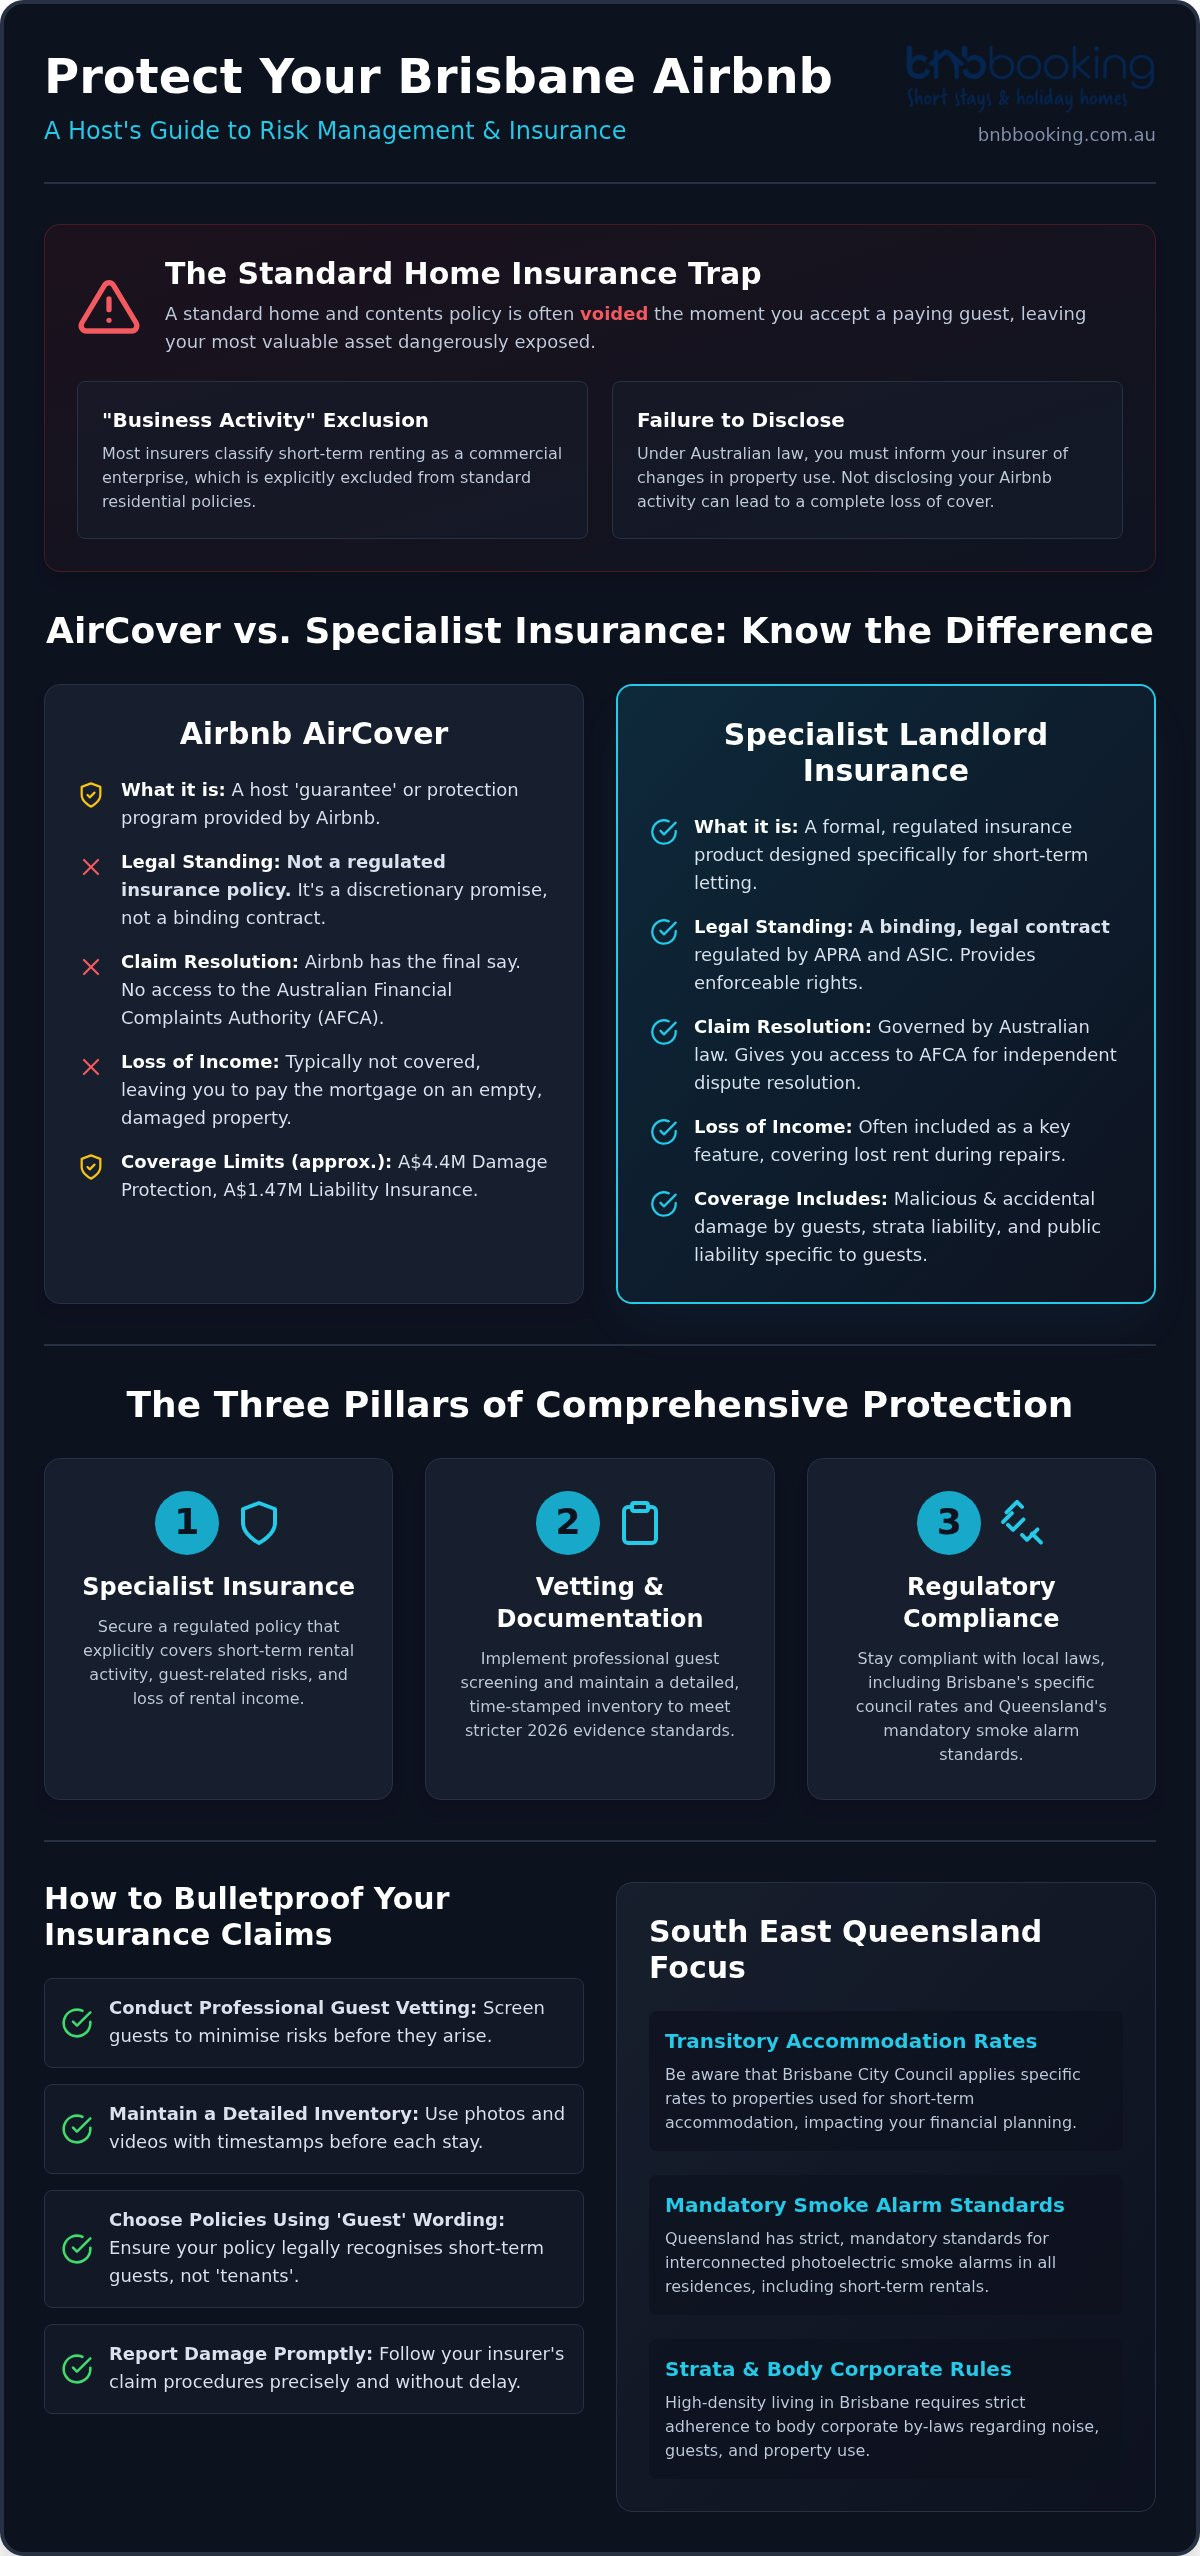
Securing a specialist policy is only half the battle. To ensure your claims are actually paid, you must demonstrate a high level of professional oversight. In the context of airbnb risk management australia, this means shifting from a passive hosting style to an active, evidence-based approach. Insurers look for any reason to deny a claim, and a lack of documentation or poor guest vetting are the most common points of failure.
Prevention is invariably more cost-effective than a claim. Effective screening begins with professional communication services that filter out high-risk bookings before they ever set foot in your Brisbane property. Red flags often include unverified profiles, vague reasons for travel, or local residents attempting to book for a ‘quiet night’ which often masks an unauthorised party. By establishing a robust house rule policy that explicitly bans such activities, you create a legal basis for your insurance claim if those rules are breached and damage occurs.
Following the April 20, 2026, updates to platform evidence standards, the window for reporting damage has become incredibly narrow. You need a digital paper trail that begins before the guest arrives. This includes high-resolution, time-stamped photography of every room during each turnover to prove the state of the property. Professional cleaning reports also act as a documented ‘health check’, proving the home was in good condition. Furthermore, using a preventative maintenance checklist shows you’ve fulfilled your duty of care as a host, making it much harder for an insurer to claim the damage was due to neglect.
If a guest causes damage, having a professional management team in place is your greatest asset. We handle the immediate evidence gathering, coordinate repairs, and manage the complex communication with both the platform and your insurer. This proactive stance is a cornerstone of airbnb risk management australia, keeping your property ‘insurable’ by maintaining high standards that commercial providers respect. If you want to ensure your investment is protected by experts who understand the SEQ market, contact BnB Booking for full-service management today.
Professional property management is the final, most critical layer of airbnb risk management australia. While specialist insurance provides the financial safety net, our full-service management provides the active oversight required to prevent claims from being necessary in the first place. We transition your property from a vulnerable self-managed listing to a professionally shielded asset, ensuring every guest stay is governed by rigorous standards that protect both your physical property and your personal liability.
Our approach is specifically tailored for the Brisbane and South East Queensland markets, where local regulations and Body Corporate sensitivities demand a sophisticated touch. We don’t just manage bookings; we manage the complex intersection of guest expectations, property maintenance, and legal compliance. By integrating these professional standards, we elevate airbnb risk management australia from a theoretical concept to a practical, daily reality for our owners.
Self-management platforms often fail because they lack a physical presence at the property during critical windows. Our professional cleaning and linen services do more than just prepare a home for the next guest; they serve as a primary risk assessment tool. Every turnover is an opportunity to spot minor issues, such as a damp patch on a ceiling or a loose balcony rail, before they escalate into major insurance events. We maintain a network of local Brisbane tradespeople on call for emergency repairs, which is essential for preventing secondary damage that insurers might otherwise refuse to cover. Additionally, our expertise in SEQ Body Corporate rules ensures your property remains compliant with local bylaws, protecting the validity of your specialist landlord policy.
When an incident occurs, the pressure to gather evidence within strict platform-mandated timelines can be overwhelming for individual owners. We remove this stress by providing the structured, professional documentation that Australian insurers and brokers require for fast payouts. From high-resolution inventory logs to detailed maintenance records, we ensure your claim is backed by undeniable proof that meets the 2026 evidence standards. As your primary liaison, we handle the disputes and the paperwork, allowing you to enjoy the rewards of your investment without the administrative burden of risk mitigation. Protect your property with BnB Booking management today.
Successful property investment in 2026 requires more than just a beautiful listing; it demands a proactive approach to airbnb risk management australia. We’ve explored why standard home policies fall short and why relying solely on platform guarantees like AirCover leaves significant gaps in your protection. By focusing on the three pillars of liability, contents, and revenue protection, you transform your property into a resilient commercial asset that can withstand the unexpected.
At BnB Booking, we specialise in the Brisbane and South East Queensland markets, providing the boots-on-the-ground presence needed to mitigate risk. Our team delivers professional maintenance coordination and rigorous guest vetting systems designed to keep your home safe and your insurance valid. Don’t leave your financial future to chance or discretionary platform policies. Get a Free Management Appraisal and Risk Assessment today to ensure your property is fully protected. With the right strategy and professional support, you can host with absolute confidence and watch your investment thrive.
AirCover is a discretionary guarantee provided by the platform, but it isn’t a comprehensive insurance policy. While the 2026 limits provide approximately A$1.47 million in liability protection, this often falls short of the A$20 million required by many Brisbane Body Corporates. Because it’s not a regulated insurance product, you don’t have access to the Australian Financial Complaints Authority if a claim is denied. We always recommend a specialist policy to ensure your assets are truly protected.
Most standard landlord policies specifically exclude short-term stays, often defining ‘tenancy’ as a period of 90 days or more. If you host guests for profit without a specific short-stay endorsement, you’re likely in breach of the ‘business activity’ exclusion clause. This can result in your entire claim being rejected, even for unrelated events like fire or storm damage. You must disclose your short-term rental activities to your insurer to maintain valid coverage.
Costs vary based on your property’s value and location, but a contents-only policy for a Queensland rental was approximately A$550 to A$600 per year in late 2025. Comprehensive building and liability policies will be higher. While price is a factor, the focus should be on the policy’s definitions. Ensure your cover explicitly includes ‘short-term guests’ rather than just ‘tenants’ to avoid legal complications during the airbnb risk management australia process.
Public liability covers you if a guest or third party is injured or killed on your property, protecting you against massive legal lawsuits. Damage protection covers the physical structure and your belongings from events like fire, flood, or theft. For Australian hosts, liability is the most critical pillar because a single ‘trip and fall’ claim can exceed the value of the property itself. Both are essential for a complete risk strategy.
Yes, Brisbane strata buildings have strict requirements regarding short-term accommodation. Most Body Corporates in South East Queensland mandate that owners carry A$20 million in public liability insurance to cover incidents in common areas. Failing to provide proof of this insurance can lead to fines or legal action from the committee. We specialise in navigating these complex strata rules to ensure your investment remains compliant and welcomed within your building.
Several niche providers in Australia offer pay-per-night insurance, which can be useful for casual hosts. However, for a dedicated investment property, an annual specialist policy is usually more cost-effective and provides broader protection. Pay-per-night options often have more exclusions and may not satisfy the high liability limits required by Brisbane strata committees. A professional management team can help you assess which model best fits your specific airbnb risk management australia needs.
General wear and tear, such as scuffed walls or slightly faded linens, is almost never covered by insurance. Policies are designed to protect against sudden, accidental, or malicious events, not the gradual deterioration that comes with regular use. This is why professional maintenance coordination is so vital. We treat wear and tear as an operational expense, ensuring your property stays in top condition through proactive upkeep rather than relying on insurance for minor cosmetic issues.
You must act quickly by documenting the damage with time-stamped photos and video immediately after discovery. Under 2026 AirCover rules, you have a strict 14-day window to submit a claim. If you have specialist insurance, notify your broker or insurer alongside the platform report. For our clients, we handle this entire evidence-gathering and dispute process, coordinating with local tradespeople to get the property repaired and back on the market without delay.